As-Completed Value on a Construction Loan
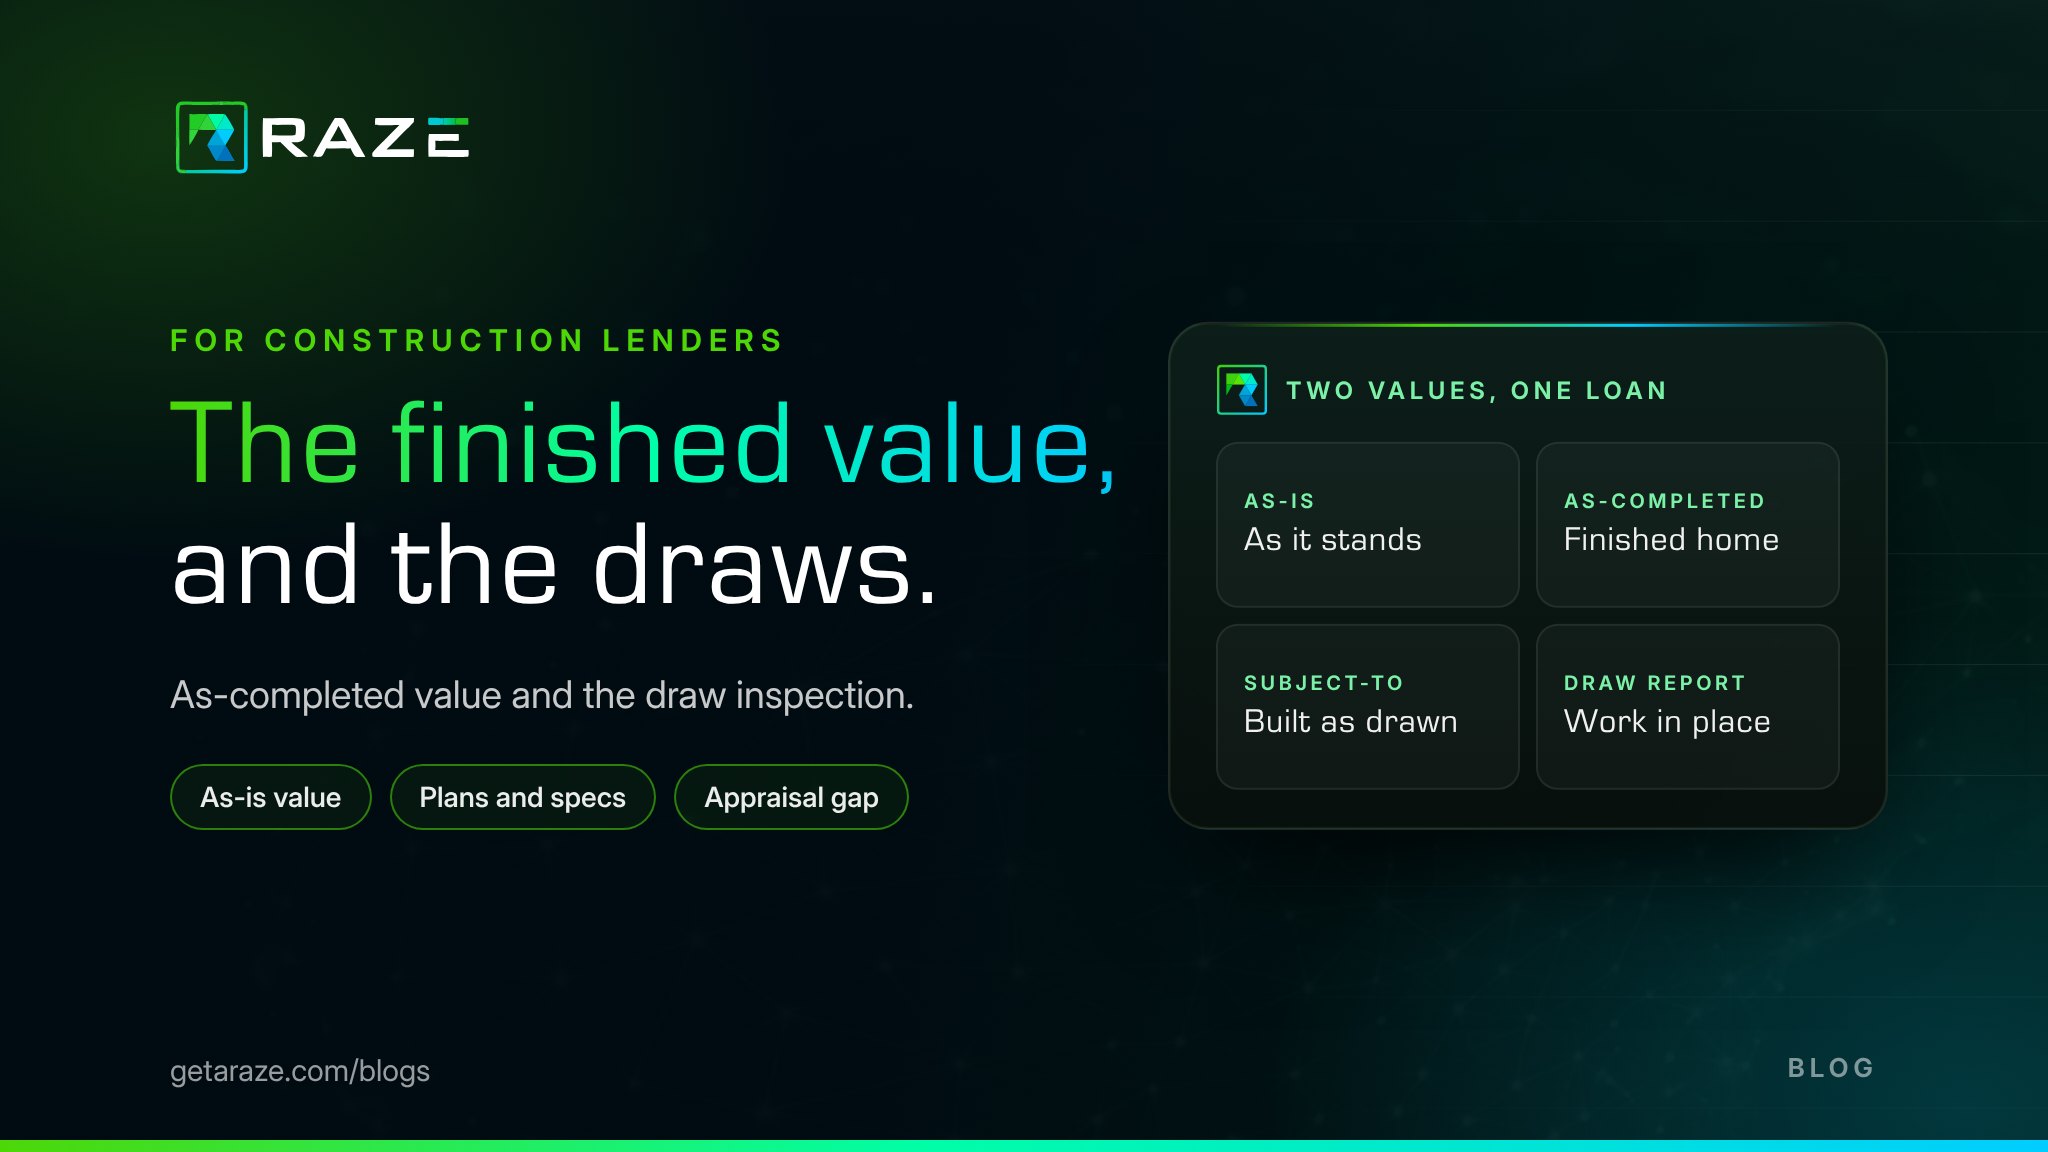
A construction loan is underwritten against a house that does not exist yet. The as-completed value on the appraisal is a value for the finished home. Every draw between closing and completion moves money toward that finished home, one stage at a time.
As-completed value is the appraised value a property is expected to have once construction is finished, used to underwrite construction loans. This guide covers the values and appraisals a draw desk meets. A draw inspection is not a valuation, and RAZE does not appraise. This page makes no claim about how value is set; the appraiser and the lender's appraisal process decide that.
Five terms behind the value
| The term | What it is | The detail that matters |
|---|---|---|
| As-is value | What it isThe current market value of a property in its present condition | The detail that mattersBefore any construction or improvement |
| As-completed value | What it isThe appraised value a property is expected to have once construction is finished | The detail that mattersUsed to underwrite construction loans |
| Plans and specs appraisal | What it isAn appraisal of a not-yet-built home based on plans, specifications and the cost breakdown | The detail that mattersIt produces an as-completed value |
| Subject-to appraisal | What it isAn appraisal made subject to completion of proposed construction or repairs | The detail that mattersValue is conditioned on that completion |
| Appraisal gap | What it isThe shortfall when appraised value comes in below purchase price or projected cost | The detail that mattersIt requires extra borrower equity |
Loan-to-value is the ratio of the loan amount to the appraised value of the property, a core measure of lender risk exposure. On a construction loan, the value in that ratio is a promise about the future. The short answer on as-is versus as-completed value puts the two side by side.
Where each value meets the loan
Before closing
The appraisal is an independent, licensed opinion of value. For a construction loan it is typically a plans and specs appraisal that produces an as-completed value from the drawings, the specifications and the cost breakdown.
When the numbers do not meet
An appraisal gap requires extra borrower equity. The construction loan equity guide covers cash, land and sweat equity.
At every draw
The draw inspection answers a different question: how much of the work is done. It records percent complete by line item with photographs and carries no opinion of value.
When the plans change
A stack of draw reports does not tell you whether the as-completed value still holds after change orders. That question goes back to the lender's appraisal process.
At completion
The subject-to condition on the appraisal is about completion. A completion report on the valuation side, which Fannie Mae's Selling Guide describes, is a separate document from the lender's final draw inspection, even when both are ordered in the same week.
A draw inspection is not an appraisal.
An appraisal answers what the property is worth. A draw inspection answers how much of the work is in place. A risk policy should name both, with who orders each and when.
Why the inspection still matters to value
The as-completed value assumes the house gets built as drawn. The draw inspection is the dated record of whether it is being built, stage by stage, against the approved budget. When the record shows a line funded ahead of the work, the money gets ahead of the work. The percent complete guide covers how that gap shows up on a draw sheet.
The live answer, is a draw inspection the same as an appraisal, covers who performs each and the standards an appraisal follows.
Where RAZE fits
RAZE documents the work; the lender decides what to fund. RAZE is the progress-verification layer, not the valuation layer. Appraisals stay with the lender's appraisal management process.
Each photo carries GPS coordinates and date and time stamps and is linked to the draw sheet line it supports. RAZE does not approve, deny or fund draws.
Frequently asked questions
Keep reading
The appraisal sets the value. The draws track the work.
See progress by line item, with photos tied to each line.
For Lenders
See a draw inspection on a project in your book, from order to delivered report.
Get StartedThe appraisal values the finished house.The inspection shows how far it got.
Read every draw against the work in place.
Get Started