The home is occupied
Visits are scheduled with the household, and the photos stay on the work areas the draw pays for.
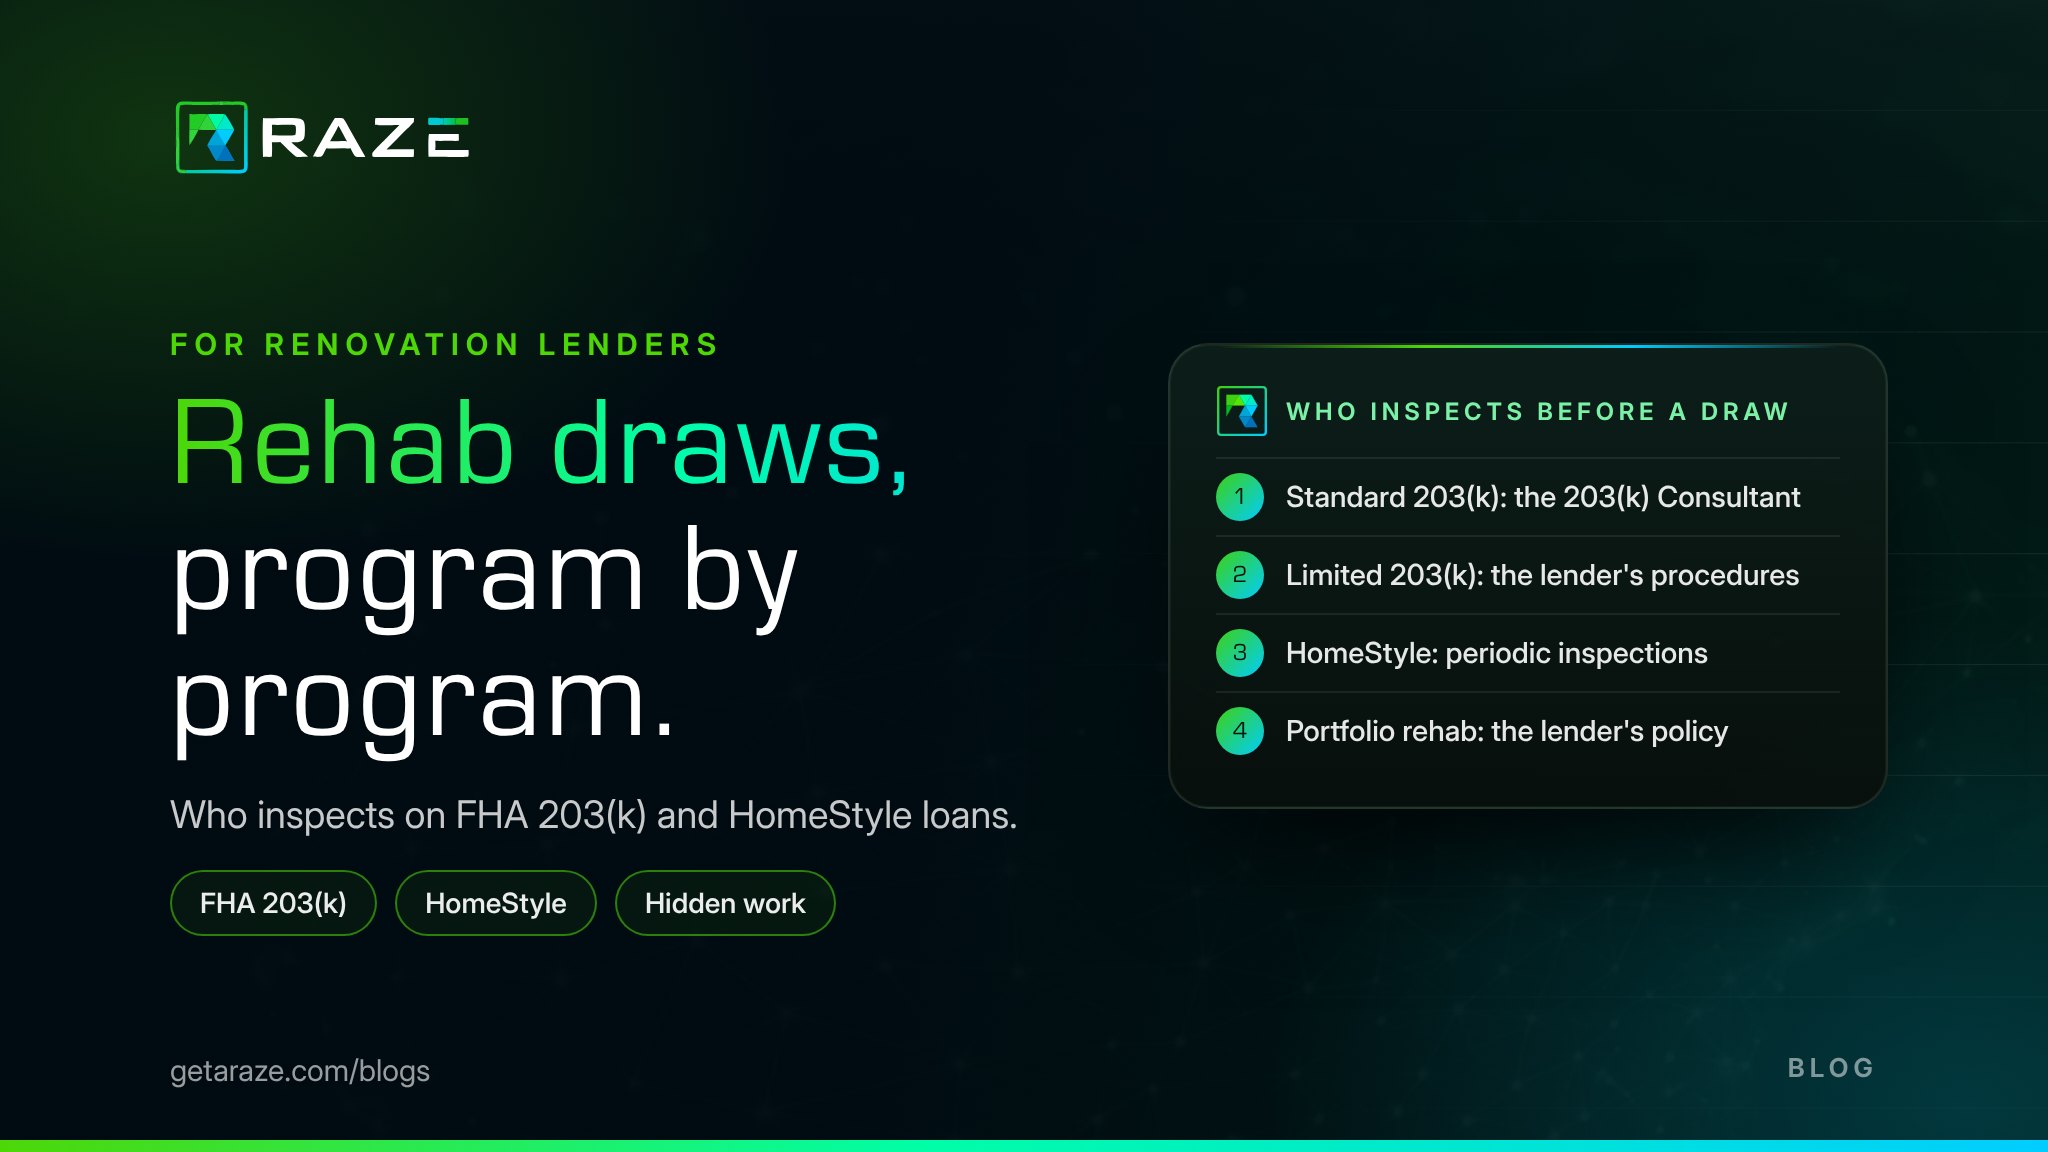
A renovation draw is not a smaller construction draw. The house already stands, the family may still live in it, half the work disappears behind drywall, and the scope can change the day a wall comes open. The loan program also decides who inspects, which is not true of most construction loans.
This guide sets the two best-known renovation programs, FHA 203(k) and Fannie Mae HomeStyle Renovation, side by side, then covers what a lender's own renovation draw policy needs. The short answers live on their own pages: who inspects a 203(k) draw, how HomeStyle draws work and what a rehab draw inspection is.
| Program | Who inspects before a draw | How funds are released |
|---|---|---|
| Standard 203(k) | Who inspects before a drawA HUD-approved 203(k) Consultant, required on every Standard 203(k), who signs the draw request | How funds are releasedFrom a rehabilitation escrow account, in draws, after the consultant's inspection |
| Limited 203(k) | Who inspects before a drawNo consultant is required, though one may be used; otherwise the lender's procedures decide | How funds are releasedUp to four draw requests per contractor since June 2026, including the initial and final draws |
| HomeStyle Renovation | Who inspects before a drawPeriodic inspections confirming the work matches the plans before each later draw | How funds are releasedUp to 50 percent of planned renovation costs at closing, the rest from escrow |
The 203(k) rows come from HUD's Handbook 4000.1 (updated August 12, 2026), which requires a consultant on the Standard 203(k), makes one optional on the Limited 203(k) and caps the Limited program's total rehabilitation costs, and from Mortgagee Letter 2026-06 (June 23, 2026), which raised the Limited 203(k) draw limit to four per contractor: the initial draw at closing, up to two intermediate draws and the final draw. The same letter did not add draws to the Standard 203(k), says the lender is not required to inspect a Limited 203(k)'s completed work but may, and limits how many third-party inspections the lender may charge to the borrower. The consultant signs HUD's draw request form, and HUD's consultant fee schedule caps what a consultant may charge for each draw inspection.
The HomeStyle row comes from Fannie Mae's Selling Guide, section B5-3.2-04, and Servicing Guide section D1-2-01. At the end, completion is documented on Form 1004D from a renovation consultant, architect or appraiser. Both agencies revise these rules, so read the current Handbook 4000.1 and Guide text before setting procedure.
On a Standard 203(k), the consultant's inspection and HUD's forms govern each draw, and a separate inspection does not stand in for them.
Visits are scheduled with the household, and the photos stay on the work areas the draw pays for.
Wiring, plumbing and insulation are visible only until the walls close, so the inspection that shows them has to come first.
Opening a wall can turn up rot or old wiring. Changed work is funded after its change order is approved, not before.
Portfolio renovation loans, private rehab loans and a Limited 203(k) without a consultant all leave more to the lender's own policy. Five rules keep those draws consistent.
The inspector and the reviewer should know which rules apply before the visit, since the program decides what the release needs.
Percent complete is reported against the lines of the contractor's bid or scope of work, not against the house as a whole.
Schedule a visit at rough-in, so the hidden work is photographed while it can still be seen. See the draw inspection checklist.
The report should note work that differs from the approved scope, and the file should show the approval behind it.
HomeStyle names Form 1004D. For other loans, the lender's final inspection closes the file; see the final draw guide.
RAZE holds no role in either program's rules and is not a HUD 203(k) Consultant. Today it is a draw inspection a lender can order where its procedures call for one: interim HomeStyle draws with a third-party inspector, and portfolio or private renovation loans. Draw inspections for FHA 203(k) loans are an upcoming RAZE service and not yet available; to ask about them, Talk to Sales. In the Ordering Engine the lender sets the required questions and photos, so each program's items travel with the order. A RAZE report gives percent complete for each line of the renovation budget, with photos linked to the lines they support and GPS coordinates and date and time stamps on every photo, which keeps a record of work that will soon be behind drywall.
Through RAZE, a draw inspection is a flat $125 per single-family inspection when RAZE sends the inspector, or $25 per request with your own inspector, at any U.S. address. See the RAZE Rate Card. RAZE documents the work; the lender decides what to release.
Line-by-line progress and located, dated photos, whichever program funds the work.
See a draw inspection on a project in your book, from order to delivered report.
Request a DemoOne report format for every renovation draw.
Request a Demo